The Wrong Factory Is the Most Expensive Mistake in Brazilian Sourcing
Vista Furniture Co. is an independent sourcing consultancy in São Paulo. We work for furniture buyers, never for factories.
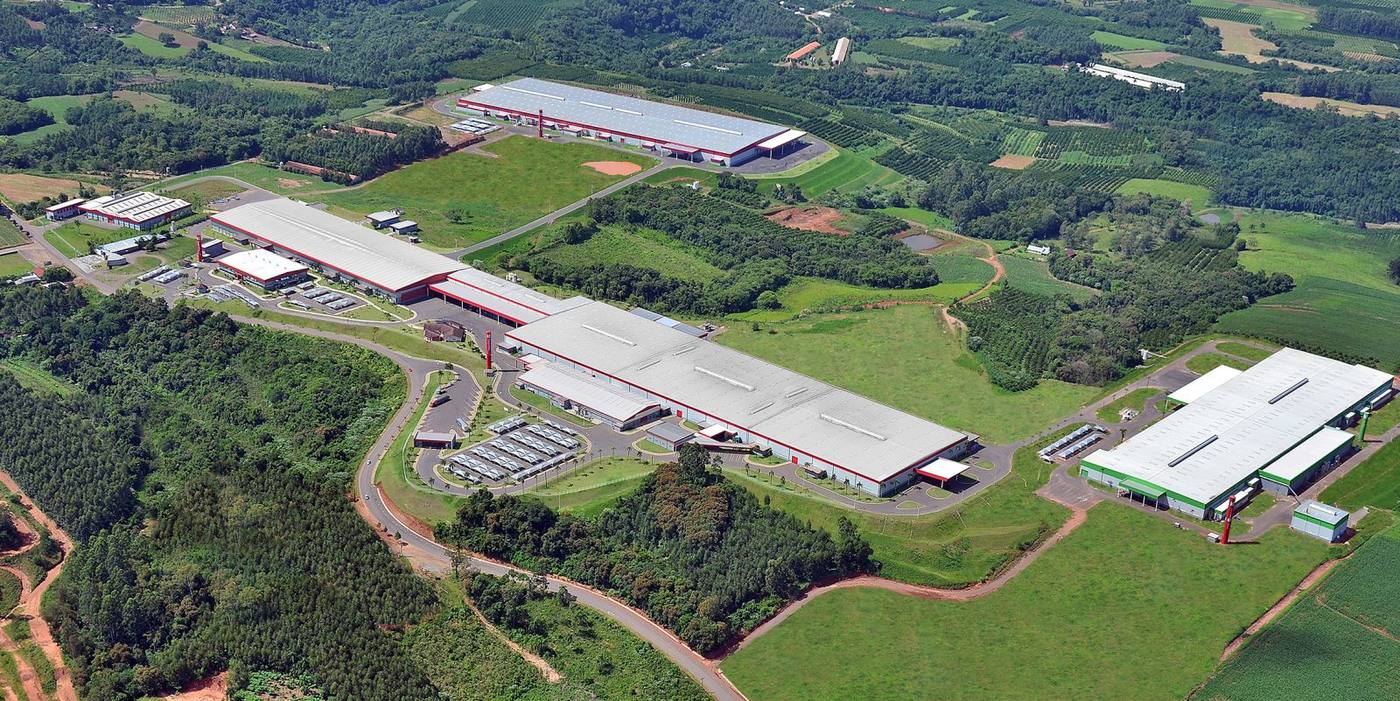
A buyer builds a list of eight Brazilian factories from a trade fair directory, sends all eight the same RFQ, and gets quotes forty percent apart on what looks like the same piece. The cheapest is implausible. The most expensive is triple the Asian benchmark. The buyer takes something near the middle, runs samples for three months, and the programme fails on a tolerance nobody discussed. The conclusion written in the sourcing report is that Brazil is expensive and slow.
That conclusion is almost always wrong, and the quote spread is the evidence. A forty percent spread across eight factories in the same country is not a price signal. It is a map. It says those eight plants were built for different materials, different run sizes and different customers, and that most of them were never candidates for this programme. The buyer did not have a Brazil problem. The buyer had a factory problem, and no way to see it from the outside.
This is the failure mode we are called in to undo most often, usually after it has already cost a season. It is worth setting out how it happens.
A cluster is registering its name to stop exactly this
In the Planalto Norte of Santa Catarina, around São Bento do Sul and Rio Negrinho, sits a furniture cluster more than a century old. German, Polish and Czech settlers built it in the nineteenth century, and the first industrial output was barrels for erva-mate. It turned to export in the 1980s and has been one of Brazil's main furniture export origins since.
What makes it unusual is the material. According to Sebrae, which is preparing the cluster's application, solid wood accounts for about 95 percent of what São Bento do Sul produces, while panel is the main raw material in roughly 95 percent of Brazil's other furniture clusters. Native imbuia gave way to plantation pine decades ago for environmental and legal reasons, but the working tradition stayed in timber rather than moving to board.
The cluster is now filing for a Geographical Indication with INPI, Brazil's patent and trademark office. The dossier is due in November 2026 and confirmation is expected by the end of 2027. The stated purpose is to separate furniture that is genuinely solid wood from furniture made with panels and sold on the region's reputation. Sebrae's Luiz Carlos da Silva put it bluntly to Gazeta do Povo: there are plenty of people in Brazil selling furniture by misleading the customer.
Read that as a buyer rather than as a consumer. A century-old cluster is spending two years and a legal filing to make a distinction that it cannot otherwise force a quote to reveal. If the industry itself needs a registered mark to tell solid wood from panel at the point of sale, an overseas buyer working from a website, a fair stand and a PDF has no chance of doing it from a desk.
Four ways a buyer lands on the wrong factory
The mistake is rarely stupidity. It is almost always a reasonable assumption that does not survive contact with how the Brazilian industry is actually organised.
1. The wrong material for the cluster
Quoting a solid wood dining programme in a panel cluster produces a high number, because the plant has to buy in the timber, outsource the machining it does not have, and price the risk of work it does not normally do. Quoting a panel casegoods programme in a solid wood cluster produces the same distortion in reverse. Neither number tells you what the piece costs in Brazil. Both tell you that you called a factory that would have to reorganise itself to serve you.
The regional map of Brazilian furniture manufacturing sets out which materials sit where. The short version is that the South and São Paulo account for most of the industry, and that they are not interchangeable: Santa Catarina's Planalto Norte works timber and will quote ready-to-assemble in solid wood, while panel furniture concentrates in Arapongas, Bento Gonçalves, Mirassol and Votuporanga. Caçador, in the same state as the solid wood cluster, is where the panel itself is milled.
2. The wrong market orientation
Arapongas, in Paraná, is the single municipality that makes the most furniture in Brazil, with around 270 furniture companies and roughly 10,000 direct jobs. It is also, by its own industry association's account, a cluster that sells about 90 percent of its output into other parts of Brazil.
That is not a weakness. It is a design. A plant built to ship pallets to Brazilian retail chains has engineered its cartons, its lead times, its documentation and its commercial terms around a domestic customer who takes delivery by truck in four days and returns damaged goods the same week. Ask it for export cartons, a packing list that will clear US customs, CARB or TSCA Title VI documentation and a thirty day ocean leg, and none of that exists yet. It can usually be built. It has not been built. A quote that does not price the building of it is a quote you cannot use, and the factory is not being dishonest, it simply answered the question you asked.
Export readiness is a separate qualification from manufacturing capability, which is why we treat it as its own step and why identifying genuinely export-ready manufacturers is most of the work at a fair.
3. The wrong scale
Brazil's clusters hold an enormous range of plant sizes within a few kilometres of each other. In the Arapongas region one maker runs around fifty people building tables and chairs for decor retail, while another runs about five hundred on serial living room furniture and exports a quarter of its output to more than fifty countries. In São Bento do Sul, a single exporter produces up to 32,000 units a month for European and North American buyers.
A fifty person workshop quoted for 32,000 units will either decline or quote a number that protects it from a job it cannot take. A five hundred person serial line quoted for eighty pieces will do the same, from the opposite direction. Both quotes look like price. Neither is.
This is also where minimum order expectations go wrong. Across our network a first order usually starts somewhere between USD 10,000 and 20,000, but that is a planning figure rather than a rule, and it moves with the factory, the category and the run behind the piece.
4. The wrong channel
Most buyers build their first Brazilian list at a trade fair, and a fair's exhibitor list is a segment of the industry rather than the industry. Movelsul, in Bento Gonçalves, is the serial and modular furniture calendar. ABIMAD is the high-end residential calendar. Each is excellent at what it covers and silent about what it does not, and a buyer who only ever sees one of them will build a shortlist that reflects the fair rather than the country. Our Movelsul guide and ABIMAD guide set out who actually shows at each.
What the spread was telling you
Go back to the eight quotes forty percent apart. Read as a map rather than as a price list, that spread usually resolves into three groups. There are factories that build this piece every week and quoted it accurately. There are factories that could build it but would have to change something to do so, and priced the change into the number without explaining it. And there are factories that cannot build it and quoted high rather than say no, because declining an inbound enquiry from an overseas buyer is not how a commercial team behaves.
Only the first group was ever a supplier. The task is not to negotiate the spread down. It is to work out which group each quote came from, which takes knowing the plant, and then to run a real comparison inside the first group alone. Done that way, Brazilian pricing stops looking erratic. We have written separately on the real cost of manufacturing in Brazil against Asia and on the costs buyers routinely leave out of that comparison.
Qualifying before you quote
The sequence that avoids this is unglamorous and it is the reverse of what most buyers do. Quoting is the last step, not the first.
- Define the piece in terms the factory floor recognises: material, construction, finish, tolerance, carton, and the run size behind the first order.
- Narrow to the clusters where that piece is normal work rather than special work.
- Qualify each candidate on export readiness and on scale fit before any pricing conversation, using a written checklist rather than impressions.
- Verify the claims that matter on the floor, because a certificate and a production line are two different things. That is what a factory audit is for.
- Quote only inside the qualified set, and compare like with like.
A buyer working alone can do this. It takes time on the ground and a tolerance for being told no, and it is how factory vetting works anywhere in Latin America. What it cannot be done from is a desk and an inbox.
What a map does not do
Knowing the clusters narrows the field. It does not pick the factory, and we would be overselling it to suggest otherwise. Inside São Bento do Sul there are plants that will fail an audit. Inside Arapongas there are exporters that will outperform anything in Santa Catarina on a panel programme. Geography tells you where a piece is normal work. It tells you nothing about whether a given plant is solvent, honest about its capacity, or capable of holding a tolerance across a production run.
That last part is floor work. It is why the method we run puts supplier vetting and factory qualification ahead of commercial conversation, and why we treat a supplier that goes silent mid-programme as a qualification failure rather than bad luck.
The cluster in São Bento do Sul has decided it needs a registered mark to prove what its furniture is made of. Until that exists, and well after it does, the only reliable way to know which Brazilian factory is right for a programme is to go and look.
Sources
- Gazeta do Povo, on the São Bento do Sul Geographical Indication filing
- Government of Paraná, on Arapongas as Brazil's largest furniture-producing municipality
- SIMA, the Arapongas furniture industry association
- Sindmóveis, on the Bento Gonçalves cluster
- BNDES, on the Brazilian furniture industry and its clusters
Matheus Ximenes Pinho is the founder and managing director of Vista Furniture Co. He has spent more than twenty years in home and décor, fourteen of them in the Brazilian furniture industry, working across product design, manufacturing, and digital retail. He advises international retailers, brands, hotel groups, and developers on sourcing furniture in Brazil with less risk and better decisions.
Vista Furniture Co. is a buyer-side furniture sourcing consultancy founded by veterans of Brazil's furniture and home industry. We work with global retailers, brands, and hospitality buyers in two ways: qualifying suppliers and reducing risk before the first order, and developing collections built for the buyer's market. We are buyer-paid and independent. You buy directly from the supplier you select. Talk to us before your next order.